Federal Student Loan Forgiveness 2026: Updates & Deadlines
Student loan debt remains a significant burden for millions of Americans, prompting continuous discussions and evolving policies around federal student loan forgiveness. As we look towards 2026, understanding the latest updates, eligibility criteria, and crucial application deadlines is paramount for borrowers seeking relief. The landscape of student aid and debt repayment is dynamic, with new programs emerging, existing ones being modified, and political shifts often influencing their trajectory. This comprehensive guide aims to demystify the federal student loan forgiveness 2026 outlook, providing you with the knowledge needed to navigate this complex terrain effectively.
Navigating the intricacies of federal student loan forgiveness can be daunting. With various programs, each possessing unique requirements and timelines, it’s easy to feel overwhelmed. However, staying informed and proactive can make a substantial difference in your financial future. Our focus here is on the programs that are expected to be active or have significant implications for borrowers in 2026, ensuring you have the most relevant and up-to-date information at your fingertips.
Whether you’re a recent graduate, a long-term borrower, or someone considering higher education, understanding the potential for student loan forgiveness is crucial. It can impact your financial planning, career choices, and overall economic stability. Let’s dive into what you need to know about federal student loan forgiveness 2026.
Understanding Federal Student Loan Forgiveness 2026: The Current Landscape
The concept of federal student loan forgiveness has been a cornerstone of higher education policy for years, aiming to alleviate the financial strain on borrowers. However, the specifics of these programs are frequently subject to change, influenced by legislative actions, presidential administrations, and economic conditions. For 2026, borrowers should anticipate a continuation of several key programs, alongside potential new initiatives or modifications to existing ones.
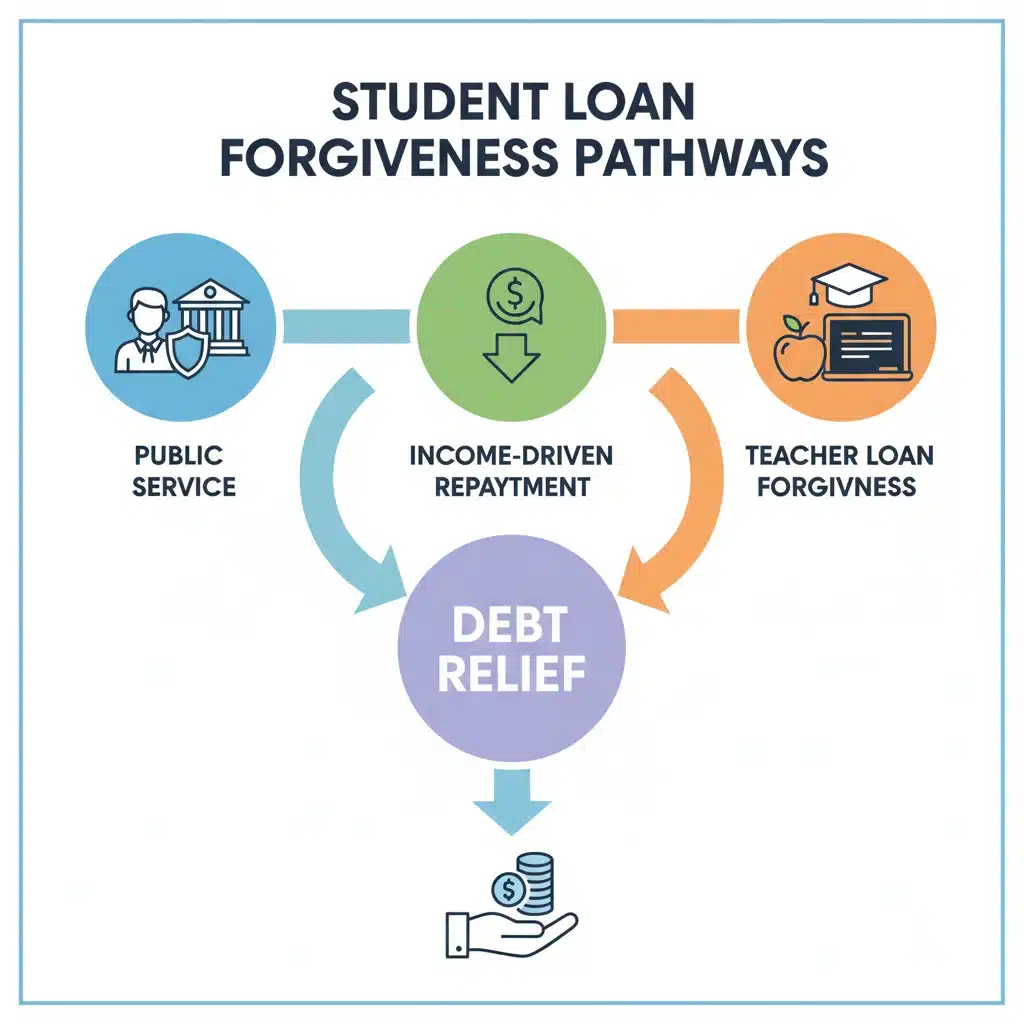
The primary mechanisms for federal student loan forgiveness typically fall into a few broad categories: income-driven repayment (IDR) plans, public service loan forgiveness (PSLF), and targeted forgiveness programs based on specific professions or circumstances. Each of these pathways offers a unique route to debt relief, but they all require diligent adherence to eligibility rules and application procedures.
It’s important to differentiate between federal and private student loans. Federal student loan forgiveness programs exclusively apply to loans issued by the U.S. Department of Education. Private loans, obtained from banks or other financial institutions, generally do not qualify for these federal programs. This distinction is critical for borrowers to understand as they explore their options for student loan forgiveness 2026.
Keeping track of policy changes is vital. What might be true today regarding eligibility or program benefits could shift by 2026. Therefore, a proactive approach to monitoring official government sources and financial aid news is highly recommended. This guide will serve as a starting point, but always verify information with the Department of Education or your loan servicer.
Key Federal Student Loan Forgiveness Programs Expected in 2026
Several established federal student loan forgiveness programs are expected to remain active and play a significant role in 2026. Understanding how each of these programs works is the first step toward determining your eligibility and planning your path to debt relief. These programs are designed to assist different segments of the borrower population, from those in public service to individuals facing financial hardship.
Public Service Loan Forgiveness (PSLF)
The Public Service Loan Forgiveness (PSLF) program is arguably one of the most well-known and impactful forgiveness initiatives. It is designed to encourage individuals to enter and remain in public service careers. Under PSLF, eligible federal student loans can be forgiven after 120 qualifying monthly payments (which do not have to be consecutive) while working full-time for a qualifying employer.
Qualifying employers include government organizations (federal, state, local, or tribal), non-profit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code, and other non-profit organizations that provide certain public services. It’s crucial to confirm your employer’s eligibility, as this is a common point of confusion for many applicants.
To qualify for PSLF, you must have Direct Loans or consolidate other federal student loans into a Direct Consolidation Loan. Payments must be made under an income-driven repayment (IDR) plan. While there have been temporary waivers and expansions of PSLF in the past, borrowers looking towards 2026 should assume standard program rules will apply unless new legislation is enacted. Regular submission of the PSLF Employment Certification Form is highly recommended to track your progress and ensure your employment and payments are being counted correctly.
Income-Driven Repayment (IDR) Plan Forgiveness
Income-Driven Repayment (IDR) plans offer another significant pathway to federal student loan forgiveness. These plans adjust your monthly loan payment based on your income and family size, making repayment more manageable. After a certain number of years (typically 20 or 25 years, depending on the plan and whether you have graduate or undergraduate loans) of qualifying payments, any remaining balance on your federal student loans is forgiven.
There are several IDR plans, including Revised Pay As You Earn (REPAYE), Pay As You Earn (PAYE), Income-Based Repayment (IBR), and Income-Contingent Repayment (ICR). Each plan has slightly different terms regarding eligibility, payment calculation, and the forgiveness timeline. Borrowers should carefully evaluate which IDR plan best suits their financial situation.
A notable development is the SAVE Plan (Saving on a Valuable Education), which replaced the REPAYE Plan. The SAVE Plan offers potentially more generous terms, including lower monthly payments for many borrowers and a shorter path to forgiveness for some. It’s expected to be a prominent option for student loan forgiveness 2026. Borrowers enrolled in older IDR plans should consider whether switching to the SAVE Plan would be beneficial. It’s important to recertify your income and family size annually to remain eligible for these plans and ensure your payments are accurately calculated.
Teacher Loan Forgiveness (TLF)
The Teacher Loan Forgiveness (TLF) program is specifically designed to encourage individuals to enter and remain in the teaching profession, particularly in low-income schools. Eligible teachers can receive up to $17,500 in forgiveness on their Direct Subsidized and Unsubsidized Loans and their Subsidized and Unsubsidized Federal Stafford Loans.
To qualify for TLF, you must teach full-time for five complete and consecutive academic years in a low-income school or educational service agency. The amount of forgiveness depends on the subject you teach. Highly qualified mathematics and science teachers at the secondary level, and highly qualified special education teachers at the elementary or secondary level, can receive up to $17,500. Other eligible highly qualified teachers can receive up to $5,000.
It’s important to note that the five years of teaching service must be completed before forgiveness can be granted. Also, borrowers cannot receive forgiveness under both PSLF and TLF for the same period of service. If you are considering student loan forgiveness 2026 as a teacher, understanding these distinctions is crucial.
Understanding Eligibility and Application Deadlines for 2026
Eligibility criteria are the bedrock of any federal student loan forgiveness program. Without meeting the specific requirements, borrowers will not be able to receive debt relief. Deadlines, too, are critical; missing them can mean missing out on significant financial benefits. As we approach 2026, it’s imperative to be meticulous about both.
General Eligibility Factors
While each program has unique requirements, some general eligibility factors apply across many federal student loan forgiveness initiatives:
- Loan Type: Most forgiveness programs, especially PSLF and IDR, primarily apply to Direct Loans. If you have Federal Family Education Loan (FFEL) Program loans or Perkins Loans, you may need to consolidate them into a Direct Consolidation Loan to become eligible.
- Employment Status: For programs like PSLF and TLF, full-time employment with a qualifying employer is a non-negotiable requirement.
- Payment History: Consistent, on-time payments are crucial. Forgiveness is typically tied to a specific number of qualifying payments.
- Application: You must actively apply for forgiveness. It is not automatic.
Critical Application Deadlines and What to Expect in 2026
For most federal student loan forgiveness programs, there isn’t a single, universal application deadline that applies to all borrowers for all programs. Instead, deadlines are often tied to specific events or the completion of required service/payments:
- PSLF: While there isn’t a hard application deadline for PSLF itself, borrowers should submit the PSLF & TEPSLF Certification & Application Form annually or whenever they change employers. This ensures your employment and payments are tracked correctly. Once you’ve made 120 qualifying payments, you apply for forgiveness.
- IDR Forgiveness: Forgiveness under IDR plans occurs automatically after you’ve made the required number of payments (20 or 25 years). However, you must annually recertify your income and family size to remain in an IDR plan and ensure your payments count towards forgiveness. Missing this annual recertification can lead to higher payments and a delay in your forgiveness timeline.
- TLF: After completing your five consecutive years of qualifying teaching service, you must apply for Teacher Loan Forgiveness. There isn’t an explicit deadline other than applying after completing the service.
As 2026 approaches, it’s wise to keep an eye on official announcements from the U.S. Department of Education and Federal Student Aid. Historically, temporary waivers or new initiatives have sometimes introduced specific, time-sensitive application windows. While we cannot predict future policy changes, staying informed through official channels is your best defense against missing out on potential opportunities for student loan forgiveness 2026.
It is also important to note that the Biden-Harris Administration has initiated several actions to provide targeted debt relief and improve existing forgiveness programs. These actions, such as the IDR Account Adjustment, have aimed to correct past administrative failures and bring millions of borrowers closer to forgiveness. While many of these adjustments have specific timelines, their impact will continue to be felt in 2026 as more borrowers become eligible for forgiveness.
Potential Changes and New Initiatives for Student Loan Forgiveness 2026
The landscape of federal student loan forgiveness is rarely static. Legislative proposals, administrative actions, and judicial reviews can all introduce new programs or significantly alter existing ones. While specific predictions for 2026 are challenging, borrowers should be aware of potential areas of change.
Ongoing Discussions on Broad Forgiveness
Discussions around broader, more universal student loan forgiveness continue to be a topic of national debate. While large-scale, across-the-board forgiveness has faced legal and political hurdles, the possibility of new, targeted relief initiatives or modifications to existing programs remains. Any significant movement on this front would likely involve legislative action or executive orders, which would be widely publicized.
Borrowers should monitor news from Congress and the Department of Education for any announcements regarding new programs or expanded eligibility for existing ones that could impact student loan forgiveness 2026. Even if broad forgiveness doesn’t materialize, smaller-scale, targeted relief for specific groups (e.g., borrowers with disabilities, those who attended predatory institutions) could still be introduced or enhanced.
Administrative Actions and Program Refinements
Beyond legislative changes, the Department of Education often makes administrative adjustments to improve the efficiency and fairness of existing programs. The recent IDR Account Adjustment is a prime example, crediting borrowers with additional qualifying payments towards forgiveness. Similar administrative actions could occur before or during 2026, potentially streamlining processes or expanding eligibility for certain groups.
These refinements often aim to address past inconsistencies or make programs more accessible. For instance, efforts to simplify the PSLF application process or improve communication with borrowers are ongoing. Staying updated on these operational changes can be just as important as tracking major policy shifts for those seeking student loan forgiveness 2026.
Impact of Economic Conditions
Economic conditions can also influence the discussion around student loan debt and forgiveness. Periods of economic downturn or high inflation might prompt policymakers to consider additional relief measures to support borrowers. Conversely, a strong economy might shift the focus away from broad forgiveness towards more targeted solutions. These broader economic trends, while not directly tied to specific program rules, can shape the political will for student loan forgiveness 2026.
Strategies for Maximizing Your Chances for Student Loan Forgiveness 2026
Given the complexities and evolving nature of federal student loan forgiveness, a strategic approach is essential. Don’t wait until 2026 to start preparing; proactive steps now can significantly improve your chances of receiving debt relief.
1. Understand Your Loan Types
The first and most critical step is to know what type of federal student loans you have. Log into your StudentAid.gov account to view your loan details. Identify if you have Direct Loans, FFEL Program loans, or Perkins Loans. If you have older loan types, consider if consolidation into a Direct Consolidation Loan is necessary to qualify for certain forgiveness programs like PSLF or IDR forgiveness. Be aware that consolidating can sometimes reset your payment count for PSLF, so research thoroughly or consult your servicer before proceeding.
2. Choose the Right Repayment Plan
If you are pursuing IDR forgiveness or PSLF, enrolling in an appropriate income-driven repayment plan is non-negotiable. Use the Loan Simulator tool on StudentAid.gov to compare different IDR plans and see how they impact your monthly payments and potential forgiveness timeline. The SAVE Plan is often the most beneficial for many borrowers, but personal circumstances vary.
3. Track Your Payments and Employment
For PSLF, meticulously track your qualifying employment and payments. Submit the PSLF & TEPSLF Certification & Application Form annually or whenever you change employers. This creates a record with the Department of Education and helps you monitor your progress towards the 120 payments. For IDR plans, make sure you recertify your income and family size every year by the deadline provided by your loan servicer. Missing this can lead to capitalization of interest and higher payments.
4. Keep Excellent Records
Maintain thorough records of all your loan documents, payment confirmations, employment certifications, and correspondence with your loan servicer and the Department of Education. This documentation will be invaluable if there are any discrepancies or issues with your forgiveness application in the future.
5. Stay Informed and Proactive
Regularly check official sources like StudentAid.gov for the latest updates on federal student loan forgiveness programs. Sign up for email alerts from the Department of Education. Policy changes can happen quickly, and staying informed will ensure you don’t miss out on new opportunities or critical deadlines for student loan forgiveness 2026.
6. Seek Expert Advice
If you find the process overwhelming or have a complex loan situation, consider consulting with a reputable, non-profit student loan counselor. The Department of Education provides a list of approved agencies that can offer free or low-cost advice. Be wary of companies that charge high fees for services you can do yourself or that promise guaranteed forgiveness.
Common Pitfalls to Avoid
Even with the best intentions, borrowers can sometimes fall into traps that jeopardize their chances of receiving federal student loan forgiveness. Being aware of these common pitfalls can help you avoid them:
- Not Consolidating in Time: If you have FFEL or Perkins Loans and want to pursue PSLF or certain IDR benefits, you must consolidate them into a Direct Loan. Doing this too late can delay your eligibility or reset your payment count.
- Incorrect Employer Certification (PSLF): Many PSLF denials stem from issues with employer eligibility or incorrect employment certification forms. Ensure your employer qualifies and that your form is filled out accurately and submitted regularly.
- Missing Annual IDR Recertification: Failing to recertify your income and family size each year can lead to your payments being recalculated at a higher, non-subsidized rate, and potentially losing credit for qualifying payments towards forgiveness.
- Falling for Scams: Be highly skeptical of companies promising instant or guaranteed forgiveness for a fee. The Department of Education and its servicers will never charge you for help with loan forgiveness.
- Assuming Forgiveness is Automatic: Forgiveness programs require active participation and application. Don’t assume your loans will be forgiven without taking the necessary steps.
- Not Understanding Tax Implications: While PSLF is generally tax-free, forgiveness under IDR plans after 20 or 25 years may be considered taxable income by the IRS, depending on current tax law. This is an important consideration for your long-term financial planning.
The Future of Federal Student Loan Forgiveness Beyond 2026
While our immediate focus is on student loan forgiveness 2026, it’s also worth considering the long-term outlook. The debate over student loan debt is a persistent one, and future policy decisions will undoubtedly continue to shape the landscape of forgiveness programs.
The trend towards more targeted relief, rather than universal forgiveness, seems to be a dominant theme. This means programs like PSLF, IDR forgiveness, and specific professional forgiveness options are likely to remain central to federal strategy. However, these programs will likely continue to undergo refinements and adjustments to address their effectiveness and accessibility.
Advocacy groups and policymakers are also exploring innovative approaches to higher education financing and debt relief, which could introduce entirely new models of forgiveness in the years to come. These could include automatic enrollment in IDR plans, expanded eligibility for certain programs, or new mechanisms for addressing institutional accountability.
For borrowers, this means that staying engaged and informed will be a continuous process. The strategies outlined in this guide – understanding your loans, choosing the right repayment plan, meticulous record-keeping, and proactive information gathering – will remain relevant and essential regardless of future policy shifts. The goal is always to position yourself to take advantage of any available relief for which you qualify.
Conclusion: Preparing for Student Loan Forgiveness 2026
The prospect of federal student loan forgiveness 2026 offers hope for many borrowers grappling with significant debt. While the programs and their specific rules can be intricate, the core message is clear: informed and proactive engagement is key to unlocking potential debt relief.
By understanding the nuances of programs like PSLF, IDR forgiveness (including the SAVE Plan), and TLF, and by meticulously adhering to their eligibility criteria and application processes, you can significantly improve your chances of reducing your student loan burden. Remember to regularly check official government resources, maintain thorough records, and seek professional guidance if needed.
The journey to student loan forgiveness may be long, but with careful planning and consistent action, you can navigate the path to a more secure financial future. Start preparing now to ensure you are well-positioned for any opportunities that arise for federal student loan forgiveness 2026.
Author