Navigating 2026 Federal Student Loan Repayment Changes: Your Comprehensive Guide
Navigating 2026 Federal Student Loan Repayment Changes: Your Comprehensive Guide
The world of federal student loans is constantly evolving, and a significant transformation is on the horizon. For millions of borrowers, understanding the federal loan changes 2026 is not just important, it’s absolutely critical for financial well-being. The upcoming modifications to federal student loan repayment plans are poised to reshape how borrowers manage their debt, offering both new opportunities and potential challenges. This comprehensive guide aims to demystify these changes, providing you with the knowledge and strategies needed to navigate the future of your student loan obligations successfully.
Student loan debt remains a substantial burden for many Americans, and policymakers frequently adjust repayment programs to address affordability concerns, economic shifts, and borrower needs. The 2026 changes represent a culmination of several recent policy discussions and legislative efforts, primarily aimed at streamlining options and making repayment more manageable for a wider range of income levels. Whether you are a current borrower, a recent graduate, or preparing to enter repayment, these updates will undoubtedly impact your financial landscape. Staying informed and proactively planning is your best defense against unexpected hurdles and your best path to optimizing your repayment strategy.
In this article, we will delve into the specifics of the federal loan changes 2026, examining the key components of new and revised repayment plans, who will be most affected, and what steps you can take now to prepare. We’ll explore the nuances of income-driven repayment (IDR) plans, discuss potential impacts on loan forgiveness, and offer actionable advice to ensure you are well-positioned for the future. By the end of this guide, you will have a clear understanding of what to expect and how to adapt your financial strategy to the evolving federal student loan landscape.
Understanding the Impetus Behind the 2026 Federal Loan Changes
To truly grasp the significance of the federal loan changes 2026, it’s essential to understand the underlying reasons for these adjustments. Over the past few decades, student loan debt has escalated dramatically, becoming a major economic concern. This rise has led to increased instances of default, delayed life milestones for borrowers, and broader economic implications. In response, various administrations and legislative bodies have sought ways to alleviate this burden and create a more equitable and sustainable repayment system.
One of the primary drivers for these changes is the ongoing effort to simplify and enhance income-driven repayment (IDR) plans. Historically, IDR plans have been complex, leading to confusion among borrowers and administrative challenges for servicers. Many borrowers who could benefit from lower payments or eventual forgiveness have not enrolled or have struggled to navigate the annual recertification process. The goal of the federal loan changes 2026 is to make these plans more accessible, transparent, and effective in providing a safety net for borrowers with lower incomes relative to their debt.
Another significant factor is the desire to address the issue of interest capitalization and runaway loan balances. Under previous structures, unpaid interest could be added to the principal balance, causing loans to grow even when borrowers were making consistent payments on an IDR plan. This phenomenon, known as negative amortization, has been a major point of contention and a source of frustration for many borrowers. The upcoming changes aim to mitigate this problem, ensuring that borrowers are not penalized for adhering to their repayment terms, especially those on IDR plans.
Furthermore, the government is looking to refine loan forgiveness pathways. While programs like Public Service Loan Forgiveness (PSLF) and IDR forgiveness exist, they have often been criticized for their stringent requirements, administrative hurdles, and low success rates. The federal loan changes 2026 are expected to introduce clearer pathways to forgiveness, potentially shortening repayment periods for certain borrowers and making the promise of forgiveness more attainable. These reforms are not just about making payments easier; they are about creating a more predictable and ultimately fairer system for borrowers who have committed to higher education.
Finally, economic shifts, including inflation and changes in employment markets, also play a role. The cost of living has increased, and wages haven’t always kept pace, making it harder for graduates to manage significant student loan payments. The 2026 adjustments are, in part, an attempt to recalibrate the repayment system to better reflect current economic realities and provide greater financial flexibility to borrowers facing these pressures. Understanding these motivations helps contextualize the specific changes we will discuss, allowing you to better anticipate their impact on your personal financial situation.
Key Components of the 2026 Federal Loan Changes
The federal loan changes 2026 encompass several critical modifications to existing repayment plans and the introduction of new features designed to benefit borrowers. While the full scope of these changes is still being finalized and communicated, several key components have emerged as central to the reform efforts. It’s crucial for borrowers to familiarize themselves with these elements to effectively plan their future repayment strategies.
Expanded and Enhanced Income-Driven Repayment (IDR) Plans
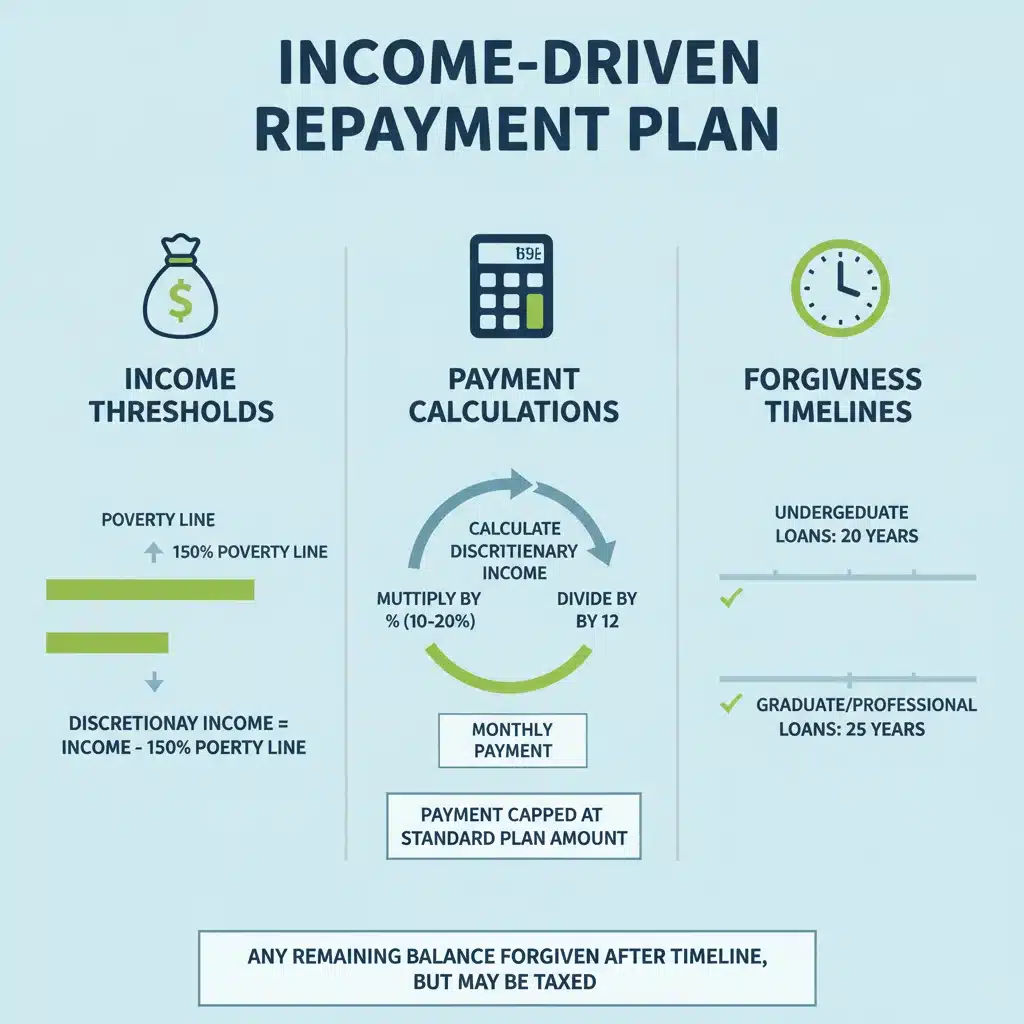
One of the most significant aspects of the federal loan changes 2026 will be the continued evolution and enhancement of income-driven repayment plans. The recent introduction of the SAVE (Saving on a Valuable Education) Plan, which replaced the REPAYE Plan, is a precursor to these broader changes. The SAVE Plan already offers more generous terms than previous IDR plans, and the 2026 changes are expected to build upon this foundation, making IDR plans even more accessible and beneficial. Key enhancements include:
- Lower Monthly Payments: For many borrowers, especially those with undergraduate loans, monthly payments under IDR plans are expected to be significantly reduced. This is often achieved by lowering the percentage of discretionary income used to calculate payments.
- Elimination of Negative Amortization: A major improvement is the elimination of interest capitalization and the prevention of loan balances growing due to unpaid interest. If your monthly IDR payment doesn’t cover the accrued interest, the government will cover the remaining interest, preventing your balance from increasing as long as you make your scheduled payments.
- Shorter Path to Forgiveness: For some borrowers, particularly those with smaller original loan balances, the time frame for loan forgiveness under IDR plans may be shortened. This means reaching forgiveness faster, potentially after 10 or 20 years of payments, depending on the original loan amount and other factors.
- Simpler Enrollment and Recertification: Efforts are underway to streamline the process of enrolling in and recertifying IDR plans, making it easier for borrowers to access and maintain their benefits. This includes potential automatic enrollment or simplified annual income verification.
These enhancements to IDR plans are central to the federal loan changes 2026, aiming to provide a more robust safety net for borrowers struggling with high debt relative to their income. They represent a fundamental shift towards making student loan repayment more manageable and less punitive.
Changes to Loan Forgiveness Programs
Beyond IDR forgiveness, the federal loan changes 2026 may also bring adjustments to other forgiveness programs, most notably Public Service Loan Forgiveness (PSLF). While specific details are still emerging, the general direction is towards clarifying eligibility, simplifying application processes, and ensuring that borrowers who dedicate their careers to public service receive the forgiveness they were promised. This could include:
- Expanded Definition of Qualifying Employment: Potentially broadening the types of employers or employment statuses that qualify for PSLF.
- Easier Payment Tracking: Improved systems for tracking qualifying payments, reducing confusion and administrative errors that have historically plagued PSLF applicants.
- Streamlined Application Process: A more straightforward and less burdensome application process for PSLF, ensuring that eligible borrowers can successfully obtain forgiveness.
These changes are designed to restore faith in loan forgiveness programs and ensure they serve their intended purpose of supporting public servants and providing relief to long-term borrowers.
Impact on Private Student Loans
It’s crucial to remember that the federal loan changes 2026 apply exclusively to federal student loans. Private student loans are issued by banks, credit unions, and other private lenders, and they are not subject to federal regulations or repayment programs. Therefore, any changes to federal IDR plans, interest subsidies, or forgiveness programs will not directly affect private loan borrowers. If you have a mix of federal and private loans, you’ll need to manage them separately, applying federal benefits only to your federal debt. This distinction is vital for accurate financial planning.
Who Will Be Most Affected by the Federal Loan Changes 2026?
The upcoming federal loan changes 2026 are designed to have a broad impact across the spectrum of federal student loan borrowers, but certain groups are likely to feel the effects more acutely than others. Understanding who these changes are intended to help, and who might need to adjust their strategies, is key to navigating the new landscape effectively.
Low- to Middle-Income Borrowers
Borrowers with lower incomes relative to their student loan debt are arguably the primary beneficiaries of the federal loan changes 2026, particularly the enhancements to income-driven repayment (IDR) plans like the SAVE Plan. The promised reductions in monthly payments, the elimination of negative amortization (where unpaid interest causes the loan balance to grow), and potentially faster paths to forgiveness are all designed to provide significant relief to this group. For many, these changes could mean the difference between struggling to make ends meet and having more financial flexibility. It could also prevent defaults and improve credit scores, opening up opportunities for homeownership and other financial goals.
Recent Graduates and New Borrowers
New graduates entering the workforce and future borrowers will also be significantly impacted. The improved IDR plans offer a more robust safety net from the outset, ensuring that initial career salaries that may not be high enough to comfortably cover standard payments won’t lead to immediate financial distress. This could encourage more students to pursue higher education without the crushing fear of insurmountable debt. For new borrowers, understanding these options from the start will be crucial in making informed decisions about loan types and repayment strategies.
Long-Term Borrowers on IDR Plans
Borrowers who have been on IDR plans for many years, diligently making payments but perhaps seeing their balances grow due to interest, will also benefit immensely. The elimination of negative amortization means that their efforts to repay their loans will finally be reflected in their principal balance, and they will no longer be fighting an uphill battle against accruing interest. Furthermore, those nearing the end of their repayment terms for forgiveness will find the process more streamlined and potentially accelerated under the federal loan changes 2026.
Borrowers with Only Undergraduate Loans
Specific aspects of the enhanced IDR plans, such as the SAVE Plan, offer more favorable terms for borrowers whose debt consists solely of undergraduate loans. The discretionary income calculation for these loans is often more generous, resulting in lower monthly payments. This is a targeted effort to alleviate the burden on individuals who pursued bachelor’s degrees and may not have the higher earning potential of those with graduate degrees.
Public Service Workers
Individuals working in public service will likely see improvements in the Public Service Loan Forgiveness (PSLF) program. While PSLF has been a lifeline for many, its complexities and high denial rates have been a source of frustration. The federal loan changes 2026 are expected to simplify and clarify PSLF requirements, making it easier for eligible public servants to achieve loan forgiveness after 10 years of qualifying payments. This reinforces the government’s commitment to supporting those who dedicate their careers to serving communities.
Borrowers Considering Refinancing Federal Loans
For borrowers who might have considered refinancing their federal loans into private loans for a lower interest rate, the federal loan changes 2026 introduce a new calculus. With enhanced IDR plans, lower payments, interest subsidies, and clearer paths to forgiveness, the benefits of federal loans are becoming even more attractive. Refinancing federal loans into private loans means forfeiting all federal protections and benefits, a decision that will become even more significant given the upcoming positive changes. Borrowers should carefully weigh these trade-offs before making any refinancing decisions.
In essence, the federal loan changes 2026 are broadly aimed at making federal student loan repayment more equitable, affordable, and less burdensome. While nearly all federal borrowers should review their options, those in the categories above will likely experience the most direct and positive impact.
Preparing for the Federal Loan Changes 2026: Actionable Steps
While 2026 might seem a ways off, proactive preparation is essential to maximize the benefits and smoothly navigate the upcoming federal loan changes 2026. Waiting until the last minute could mean missing out on crucial opportunities or facing unnecessary complications. Here are actionable steps every federal student loan borrower should consider taking now:
1. Understand Your Current Loan Portfolio
Before you can plan for the future, you need a clear picture of your present. Log in to StudentAid.gov to review all your federal student loans. Note down:
- Loan Types: Are they Direct Loans, FFEL Program loans, or Perkins Loans? Some older FFEL or Perkins loans may need to be consolidated into a Direct Consolidation Loan to qualify for the most beneficial new IDR terms and PSLF.
- Loan Balances and Interest Rates: Understand how much you owe on each loan and their respective interest rates.
- Current Repayment Plan: What plan are you currently on? Is it a standard plan, an extended plan, or an existing IDR plan (PAYE, IBR, ICR, or SAVE)?
- Payment History: Review your payment history to ensure it’s accurate, especially if you’re pursuing PSLF or IDR forgiveness.
This foundational knowledge is critical for making informed decisions regarding the federal loan changes 2026.
2. Update Your Contact Information
Ensure your contact information (mailing address, email, phone number) is up-to-date with both your loan servicer and on StudentAid.gov. This is how you’ll receive important notifications about the federal loan changes 2026, eligibility updates, and required actions. Missing critical communications could lead to missed opportunities or even administrative headaches.
3. Research the SAVE Plan (if not already enrolled)
The SAVE Plan is a key component of the ongoing reforms that will heavily influence the federal loan changes 2026. If you are not already on an IDR plan, or if you are on an older IDR plan, research the SAVE Plan’s benefits. For many, it offers the lowest monthly payments and the strongest protections against interest capitalization. Consider applying for the SAVE Plan now if it benefits you, as it will likely be the cornerstone of future IDR options.
4. Consider Loan Consolidation (Strategic Timing is Key)
For borrowers with older FFEL Program loans, Perkins Loans, or even older Direct Loans that don’t qualify for certain benefits, a Direct Consolidation Loan might be necessary. Consolidating these loans into a Direct Loan can make them eligible for the most favorable IDR plans (like SAVE) and PSLF. However, consolidation resets your payment count for IDR and PSLF forgiveness. If you are close to forgiveness under an existing plan, consult with your servicer before consolidating. The Department of Education has offered one-time adjustments for IDR and PSLF payment counts, so understanding how consolidation interacts with these adjustments is vital. This is a complex area, so seek expert advice if needed.
5. Monitor Official Communications
Stay vigilant for official announcements from the U.S. Department of Education and your loan servicer regarding the federal loan changes 2026. These communications will provide the most accurate and up-to-date information on implementation timelines, specific eligibility requirements, and any actions you need to take. Be wary of unofficial sources or scams promising quick fixes.
6. Re-evaluate Your Budget and Financial Goals
With potentially lower payments and clearer paths to forgiveness, the federal loan changes 2026 could free up financial resources. Use this opportunity to re-evaluate your budget. Could lower student loan payments allow you to save more, invest, pay down other high-interest debt, or achieve other financial goals? Align your financial strategy with the new realities of your student loan repayment.
7. Seek Professional Guidance If Needed
If your situation is complex, or you feel overwhelmed by the information, consider consulting with a non-profit student loan counselor or a financial advisor specializing in student debt. They can provide personalized advice based on your specific loan types, income, and financial goals, helping you make the most informed decisions regarding the federal loan changes 2026.
By taking these proactive steps, you can ensure you are well-prepared for the federal loan changes 2026 and position yourself to benefit from the new repayment landscape.
Potential Challenges and Considerations for Borrowers
While the federal loan changes 2026 are largely designed to benefit borrowers, it’s important to acknowledge that any large-scale systemic overhaul can present challenges and require careful consideration. Understanding these potential hurdles allows borrowers to prepare adequately and mitigate risks.
Administrative Complexity and Communication Gaps
Historically, major changes to federal student loan programs have been accompanied by administrative complexities. Loan servicers, who are responsible for implementing these changes, often face a learning curve, which can lead to delays, errors, or inconsistent information. Borrowers might experience:
- Processing Delays: Applications for new plans or consolidation might take longer to process as servicers adapt to new protocols.
- Inconsistent Information: Different representatives or departments within a servicer might provide conflicting information, leading to confusion.
- Communication Overload or Underload: Borrowers might be inundated with general information that isn’t tailored to their specific situation, or conversely, might not receive crucial updates if their contact information isn’t current.
To counter this, borrowers should maintain diligent records of all communications with their servicer, keep copies of applications, and follow up regularly. Patience and persistence will be key during the transition period of the federal loan changes 2026.
Understanding Eligibility for Specific Benefits
While the goal is simplification, the nuances of eligibility for certain benefits, especially with older loan types or specific forgiveness pathways, can still be complex. For instance, the exact terms for accelerated forgiveness for smaller balances or the specific definition of qualifying payments for PSLF might still require careful interpretation. Borrowers need to actively seek clarification and ensure they meet all criteria before assuming they qualify for a particular benefit under the federal loan changes 2026.
Impact on Future Borrowing Decisions
The federal loan changes 2026 could also influence future borrowing decisions. While federal loans are becoming more borrower-friendly, the overall cost of higher education remains high. Students and their families should continue to prioritize federal loans over private loans due to the superior protections and repayment options, but they should also remain mindful of the total debt burden. The existence of generous IDR plans shouldn’t be seen as a license to borrow excessively, as even with lower payments, large balances can still take a very long time to repay or forgive.
Tax Implications of Forgiveness
One critical consideration that often gets overlooked is the potential tax implications of loan forgiveness. While federal law currently exempts most federal student loan forgiveness from federal income tax through 2025 (and this may be extended), state tax laws vary. Some states may consider forgiven student loan debt as taxable income. As the federal loan changes 2026 potentially accelerate forgiveness for more borrowers, understanding these state-specific tax implications will become increasingly important. Borrowers nearing forgiveness should consult with a tax professional to prepare for any potential tax liability.
Staying Informed in an Evolving Landscape
The landscape of student loan policy is dynamic. While the federal loan changes 2026 provide a framework, further adjustments or new policies could emerge. Borrowers must commit to staying informed through official channels, as policies can be refined or expanded based on economic conditions or legislative action. This continuous engagement is vital for long-term financial planning.
By being aware of these potential challenges and maintaining a proactive stance, borrowers can navigate the transition period of the federal loan changes 2026 with greater confidence and ensure they are making the best decisions for their financial future.
Conclusion: Embracing the Future of Federal Student Loan Repayment
The federal loan changes 2026 represent a significant pivot in how federal student loan debt is managed and repaid. These reforms, driven by a desire for greater affordability, equity, and simplicity, aim to provide substantial relief and clearer pathways to financial stability for millions of borrowers. From enhanced income-driven repayment plans that offer lower monthly payments and protect against ballooning interest, to streamlined forgiveness programs like PSLF, the future of federal student loan repayment is poised to be more borrower-friendly than ever before.
However, the benefits of these changes will not automatically materialize. Borrowers must take an active role in understanding their specific loan situation, staying informed about official announcements, and proactively adjusting their repayment strategies. The steps outlined in this guide – from reviewing your loan portfolio and updating contact information to researching the SAVE Plan and considering strategic consolidation – are not merely suggestions; they are essential actions for maximizing the advantages offered by the federal loan changes 2026.
While potential challenges like administrative complexities and the need to understand specific eligibility criteria exist, these can be overcome with diligence and, if necessary, professional guidance. The overarching message is one of empowerment: with the right information and proactive planning, you can navigate these changes successfully and take control of your student loan debt.
Embrace this opportunity to re-evaluate your financial goals and align them with the new realities of federal student loan repayment. The federal loan changes 2026 are not just about policy; they are about providing a more sustainable and less stressful financial future for borrowers across the nation. By staying informed and acting decisively, you can transform the burden of student debt into a manageable part of your financial journey.